September 29, 2026
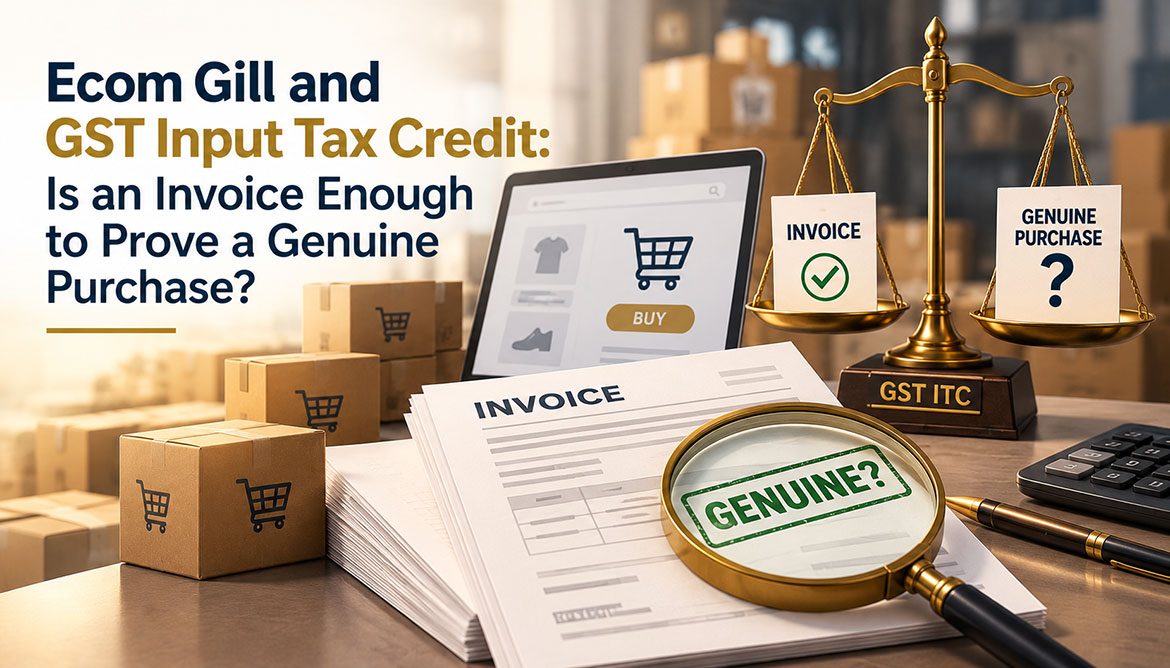
An invoice, payment through banking channels and a registered supplier may seem sufficient to support an ITC claim. The Supreme Court’s decision in Ecom Gill, however, brought the question of documentary evidence and burden of proof sharply into focus.
Although the judgment arose under the Karnataka VAT law, it has frequently been referred to in GST disputes involving the genuineness of transactions and movement of goods. The article examines how far the ruling can actually be applied under GST, what a recipient may reasonably be expected to prove and why the differences between VAT and the GST framework matter.
Read the full article on TaxGuru: Supreme Court Judgment in Ecom Gill and Implications for GST ITC