September 28, 2026
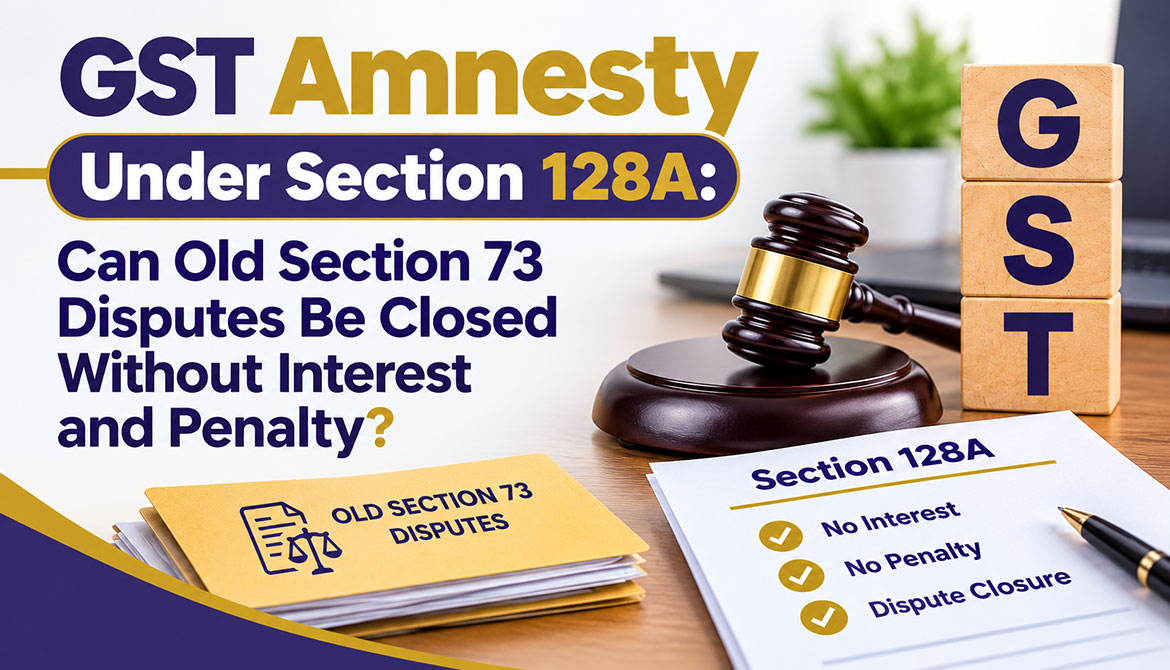
Legacy GST disputes from the early years of GST can carry a heavy interest and penalty burden, sometimes disproportionate to the original tax amount. Section 128A introduced an amnesty mechanism for specified Section 73 cases relating to the period from July 2017 to March 2020.
The relief, however, is not automatic. Eligibility depends on the stage of the proceedings, the nature of the demand and compliance with prescribed conditions. This article explains which cases are covered and how taxpayers with pending notices, adjudication orders or appeals can evaluate whether the scheme offers a practical route to closure.
Read the full article on TaxGuru: GST Amnesty Scheme for Section 73 Cases