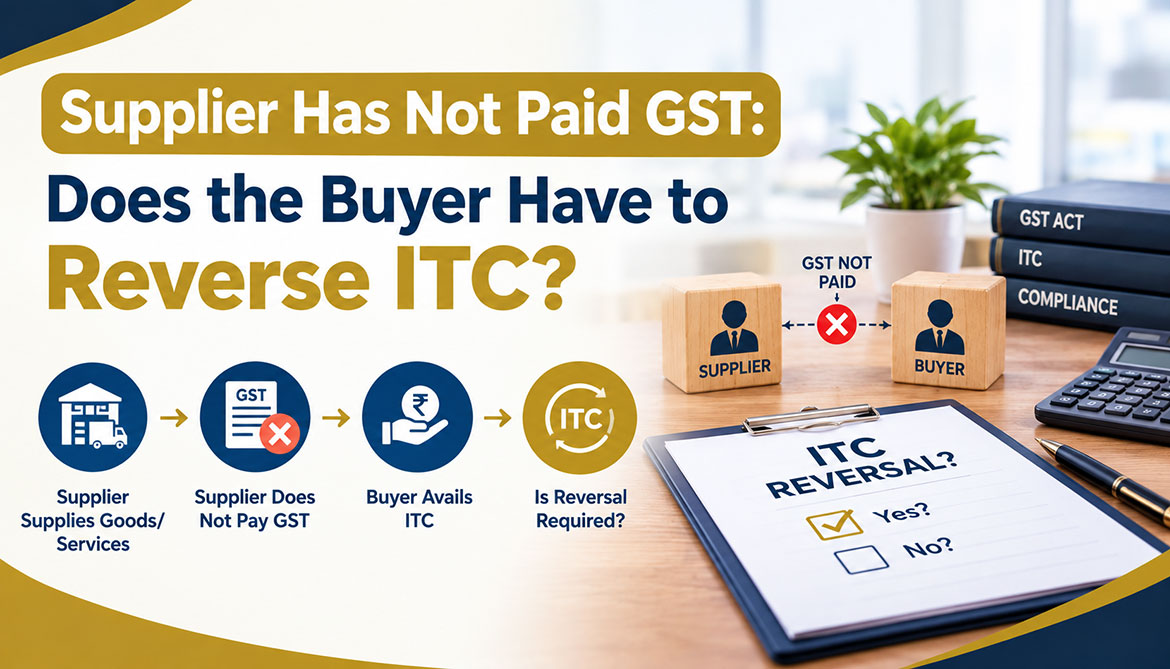
One of the most frustrating GST situations for a genuine buyer arises when the supplier defaults. You may have paid the invoice, received the goods or services and claimed Input Tax Credit — but can that credit still be questioned because the supplier has not discharged the tax?
Section 41 of the CGST Act and Rule 37A provide an important framework for dealing with such cases. The article traces how the law has evolved, when ITC reversal may actually be required, the timelines available to the recipient and when interest could arise. For finance teams managing vendor compliance and year-end ITC reconciliations, these distinctions can be critical.
Read the full article on TaxGuru: Understanding Section 41 of CGST Act and Rule 37A of CGST Rules